
 Contact
 Comment faire ses achats

Livraison
Guide d'achat
 Anglais
 368 b
Jusqu'à 30 jours pour les retours
Les clients ont également acheté




 /
 Livre de poche
 22.89
€


 /
Livre de poche
11.84
€


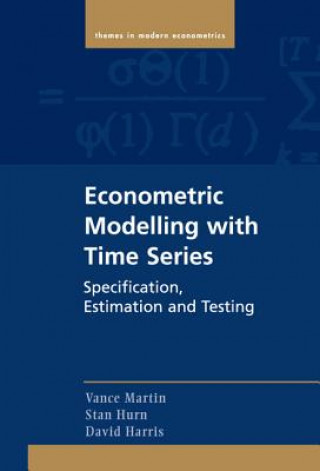
This book provides a general framework for specifying, estimating and testing time series econometric models. Special emphasis is given to estimation by maximum likelihood, but other methods are also discussed, including quasi-maximum likelihood estimation, generalized method of moments estimation, nonparametric estimation and estimation by simulation. An important advantage of adopting the principle of maximum likelihood as the unifying framework for the book is that many of the estimators and test statistics proposed in econometrics can be derived within a likelihood framework, thereby providing a coherent vehicle for understanding their properties and interrelationships. In contrast to many existing econometric textbooks, which deal mainly with the theoretical properties of estimators and test statistics through a theorem-proof presentation, this book squarely addresses implementation to provide direct conduits between the theory and applied work.


À propos du livre
Anglais

Offrez ce livre dès aujourd'hui
C’est simple
1 Ajouter au panier et choisir l'option Livrer comme cadeau à la caisse. 2 Nous vous enverrons un bon d'achat 3 Le livre arrivera à l'adresse du destinataireCeci pourrait également vous intéresser


 /
Livre de poche
88.17
€




 /
Livre de poche
10.54
€
 /
Livre de poche
10.54
€


Bonjour ! Je suis Libroamiko, votre conseiller littéraire.
Comment puis-je vous aider ?