
 Contact
 Comment faire ses achats

Livraison
Guide d'achat
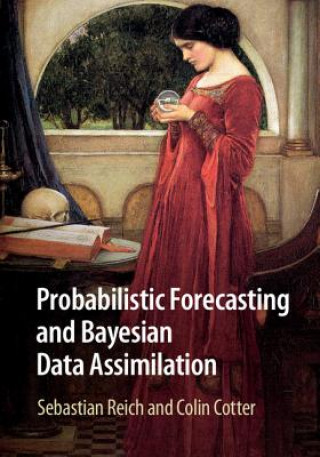
Probabilistic Forecasting and Bayesian Data Assimilation
 Anglais
 425 b
Jusqu'à 30 jours pour les retours
Les clients ont également acheté
 /
 Livre relié
 6.22
€









In this book the authors describe the principles and methods behind probabilistic forecasting and Bayesian data assimilation. Instead of focusing on particular application areas, the authors adopt a general dynamical systems approach, with a profusion of low-dimensional, discrete-time numerical examples designed to build intuition about the subject. Part I explains the mathematical framework of ensemble-based probabilistic forecasting and uncertainty quantification. Part II is devoted to Bayesian filtering algorithms, from classical data assimilation algorithms such as the Kalman filter, variational techniques, and sequential Monte Carlo methods, through to more recent developments such as the ensemble Kalman filter and ensemble transform filters. The McKean approach to sequential filtering in combination with coupling of measures serves as a unifying mathematical framework throughout Part II. Assuming only some basic familiarity with probability, this book is an ideal introduction for graduate students in applied mathematics, computer science, engineering, geoscience and other emerging application areas.


À propos du livre
Anglais

Offrez ce livre dès aujourd'hui
C’est simple
1 Ajouter au panier et choisir l'option Livrer comme cadeau à la caisse. 2 Nous vous enverrons un bon d'achat 3 Le livre arrivera à l'adresse du destinataireCeci pourrait également vous intéresser


 /
Livre de poche
27.24
€



 /
Livre relié
182.20
€


 /
Livre de poche
15.68
€

 /
Livre relié
224.83
€
 /
Livre de poche
19.40
€

Bonjour ! Je suis Libroamiko, votre conseiller littéraire.
Comment puis-je vous aider ?