
 Contact
 Comment faire ses achats

Livraison
Guide d'achat
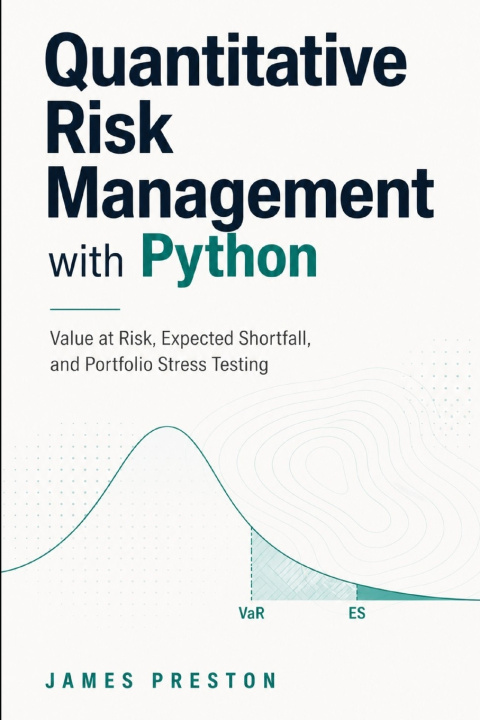
Quantitative Risk Management with Python
Value at Risk, Expected Shortfall, and Portfolio Stress Testing
 Anglais
 84 b
Jusqu'à 30 jours pour les retours
Ceci pourrait également vous intéresser


Reactive Publishing
Quantitative Risk Management with Python is a practical guide to measuring, modeling, and analyzing financial risk using modern Python workflows.
Designed for analysts, traders, students, and quantitative finance practitioners, this book explains how core risk measures are built, interpreted, and applied across real-world portfolios. Readers will learn how to calculate Value at Risk, estimate Expected Shortfall, run portfolio stress tests, analyze return distributions, and evaluate risk under changing market conditions.
The book emphasizes clear implementation, practical interpretation, and reusable Python techniques. Instead of treating risk metrics as isolated formulas, it shows how they fit into a broader risk management workflow involving data preparation, volatility estimation, scenario analysis, backtesting, and portfolio-level reporting.
Inside, readers will explore:
Value at Risk using historical, parametric, and simulation-based methods
Expected Shortfall and downside risk measurement
Stress testing and scenario analysis for portfolio exposures
Volatility, correlation, and distributional assumptions
Backtesting risk models and interpreting model limitations
Python workflows for repeatable financial risk analysis
This book is written for readers who want a structured, applied approach to quantitative risk management without unnecessary theory or promotional trading claims. It provides the tools and context needed to understand risk models, implement them in Python, and use them responsibly in financial analysis.


À propos du livre
Anglais

Offrez ce livre dès aujourd'hui
C’est simple
1 Ajouter au panier et choisir l'option Livrer comme cadeau à la caisse. 2 Nous vous enverrons un bon d'achat 3 Le livre arrivera à l'adresse du destinataireBonjour ! Je suis Libroamiko, votre conseiller littéraire.
Comment puis-je vous aider ?