
 Contact
 Comment faire ses achats

Livraison
Guide d'achat
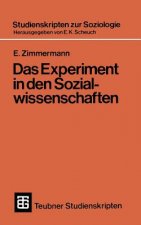
Stochastic Integrals
 Allemand
 152 b
Jusqu'à 30 jours pour les retours
Les clients ont également acheté



 /
 Livre de poche
 47.12
€

 /
Livre de poche
19.69
€

 /
Livre de poche
32.05
€
 /
Livre de poche
20.80
€


 /
Livre de poche
12.35
€


 /
 Adobe ePub DRM
3.71
€

 /
Livre de poche
16.47
€
 /
Livre relié
33.45
€


This text introduces at a moderate speed and in a thorough way the basic concepts of the theory of stochastic integrals and Ito calculus for sem i martingales. There are many reasons to study this subject. We are fascinated by the contrast between general measure theoretic arguments and concrete probabilistic problems, and by the own flavour of a new differential calculus. For the beginner, a lot of work is necessary to go through this text in detail. As areward it should enable her or hirn to study more advanced literature and to become at ease with a couple of seemingly frightening concepts. Already in this introduction, many enjoyable and useful facets of stochastic analysis show up. We start out having a glance at several elementary predecessors of the stochastic integral and sketching some ideas behind the abstract theory of semimartingale integration. Having introduced martingales and local martingales in chapters 2 - 4, the stochastic integral is defined for locally uniform limits of elementary processes in chapter S. This corresponds to the Riemann integral in one-dimensional analysis and it suffices for the study of Brownian motion and diffusion processes in the later chapters 9 and 12.


À propos du livre
Allemand

Offrez ce livre dès aujourd'hui
C’est simple
1 Ajouter au panier et choisir l'option Livrer comme cadeau à la caisse. 2 Nous vous enverrons un bon d'achat 3 Le livre arrivera à l'adresse du destinataireCeci pourrait également vous intéresser


 /
Livre de poche
17.38
€




 /
Livre relié
151.03
€
 /
Livre relié
178.47
€


 /
Livre de poche
19.28
€

Bonjour ! Je suis Libroamiko, votre conseiller littéraire.
Comment puis-je vous aider ?